
Comparing health plan prices? Estimate your yearly spending, too
It might be tempting to buy a health plan based on the lowest monthly premium, but if you do, you might be surprised by your out-of-pocket costs at the end of the year.
When you compare plan prices, it’s just as important to estimate your total yearly costs so you can find a plan that meets your needs. Here's a quick guide to help you figure that out.
 Consider what you might need to spend:
- The monthly premium, the bill you pay each month. Think of it as a fixed cost.
- Deductibles are what you must pay before your plan pays for anything except free preventive services or other no-cost services your plan might offer.
- Once you meet your deductible, you still have costs to pay for. You might pay a $25 copay, or fixed amount for a doctor visit. You also pay a share of medical costs called coinsurance, like 40% of a hospital bill, while your plan pays the rest.
- Deductibles, copayments and coinsurance add up to an out-of-pocket maximum, or the most you’ll pay in a year. Once you get there, your plan pays 100% for covered services.
Consider how much you might need:
- How much did you spend last year? Did you pay more out of pocket than you expected?
- Do you have a chronic condition that requires regular doctor visits, medications or treatments?
- Are you expecting any major costs, like surgery or pregnancy?
- Do you take monthly medications? Are any of them expensive? What is the yearly cost? Check to see if the plans you consider cover those medications. (Check Community Health Options list here.)
- Are your preferred doctors, hospitals and specialists in the plan’s network? (Check Community Health Options providers here. Note that this list can change. Contact Member Services with specific questions.)
- Do you need dental and vision coverage? Do you or your dependents wear glasses or contacts?
- What would it cost you for an unexpected trip to an Emergency Department, serious injury or illness? Do you have enough money saved to cover the expense?
Factor in non-medical considerations. If you choose a plan with a high deductible, a Health Savings Account (HSA) could allow you to lower costs saving some of your income in a tax-free account used to pay for qualified medical expenses. That's especially true now, with recent federal rules making all Marketplace Bronze plans eligible for an HSA. Talk to your broker for which options work best for you.
Want to talk with someone at Community Health Options about which plan to choose or have questions about your current plan or benefits? Please call our Maine-based Member Services team at (855) 624-6463 or email us and we’ll get back to you.
Follow @communityhealthoptions on TikTok for quick tips and tricks on how to buy and use a health plan. And don’t forget to follow Community Health Options on LinkedIn, Facebook or Instagram.
Related Blog Posts
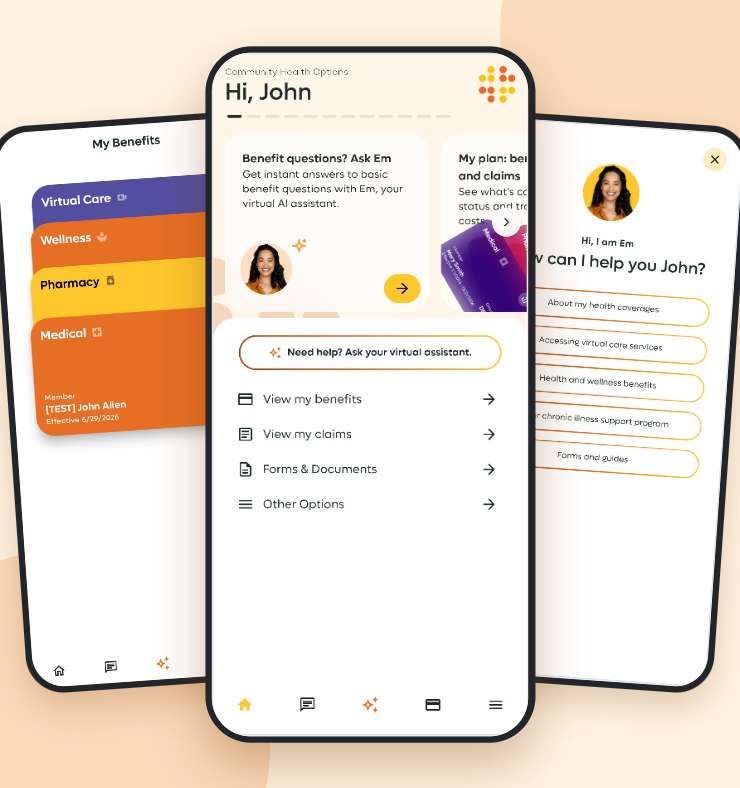
Coming soon: A simpler online tool to help Members manage their benefits
Community Health Options Members are about to get access to a new portal and mobile app so it's easier to find health plan information and understand their out-of-pocket costs.
Flu fighters: Your guide to beating the bug
The temperatures are dropping, which means flu season will soon be here. Now's a good a good time to start thinking about getting vaccinated.
Get tax-free savings for medical expenses in Bronze plans
Shopping for a health plan that you can pair with a tax-free medical savings plan? Federal HSA rules qualify all Marketplace Bronze plans as eligible for Health Savings Accounts (HSA). Here's what you need to know.